
Orlando, FL · Orange County
Public adjuster in Orlando, FL
Inland does not mean storm-proof. If your Orlando home or business was damaged by wind, water, fire or a storm, talk to a licensed Florida public adjuster before you file, or after a low offer.
- Served from our Hollywood office, 2206 Hollywood Blvd, Hollywood, FL 33020
- No fee unless you get paid
- Se habla español
Get a free claim review
A licensed public adjuster calls you back. Se habla español.
- $100M+recovered for Florida property owners
- 25+ yearscombined experience on our team
- 4.8/5★★★★★ Google rating Read our Google reviews
- No fee unless you get paidSe habla español
What we see on site in Orlando
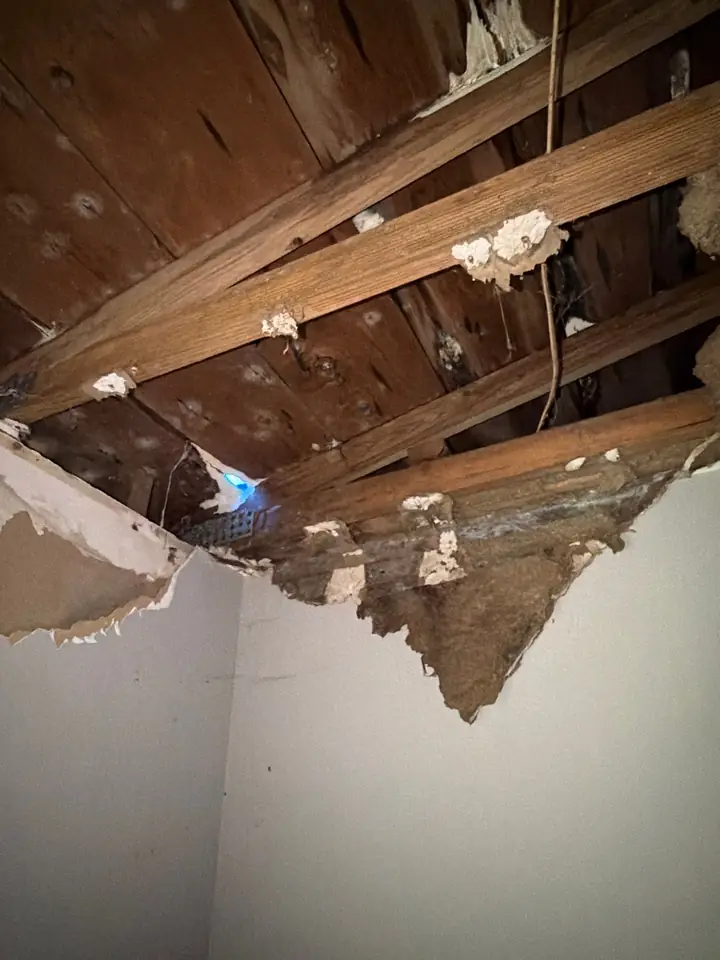
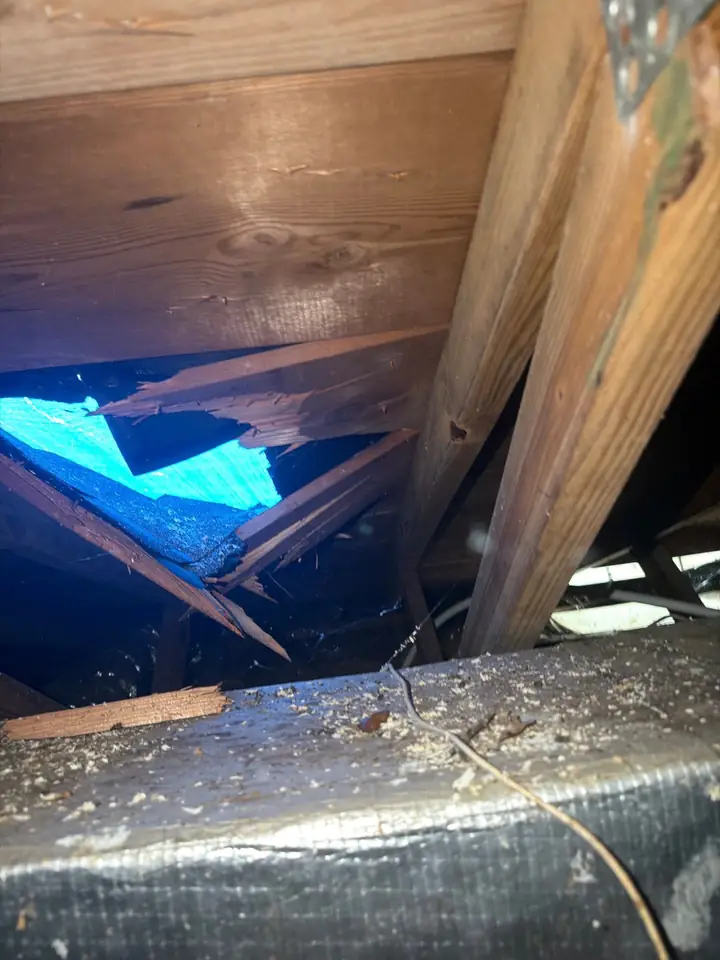
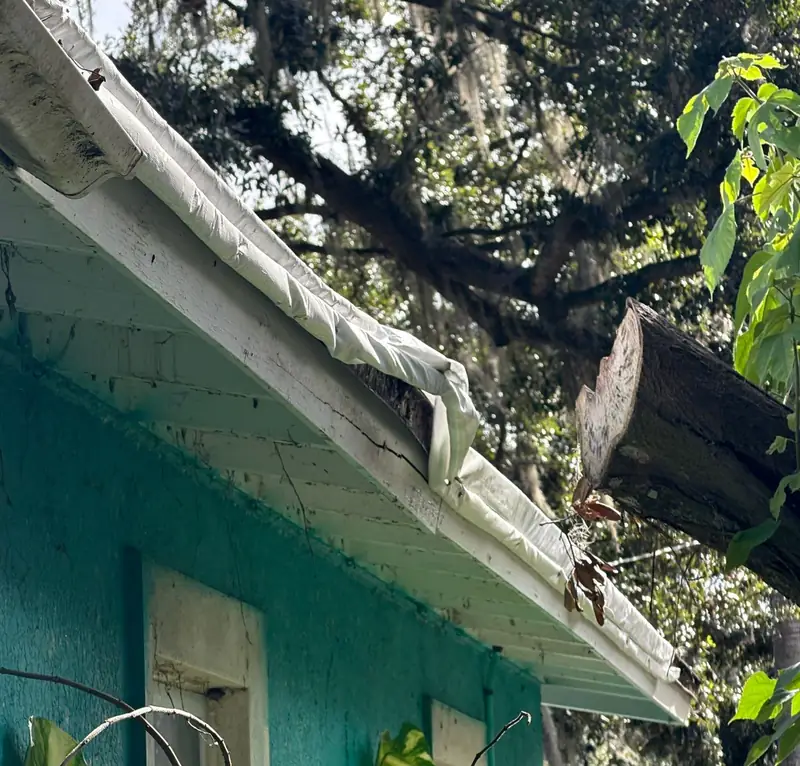
Inland damage, and an argument over the cause
Inland claims are mostly roof, water and fire claims, and the cause of loss is often disputed.
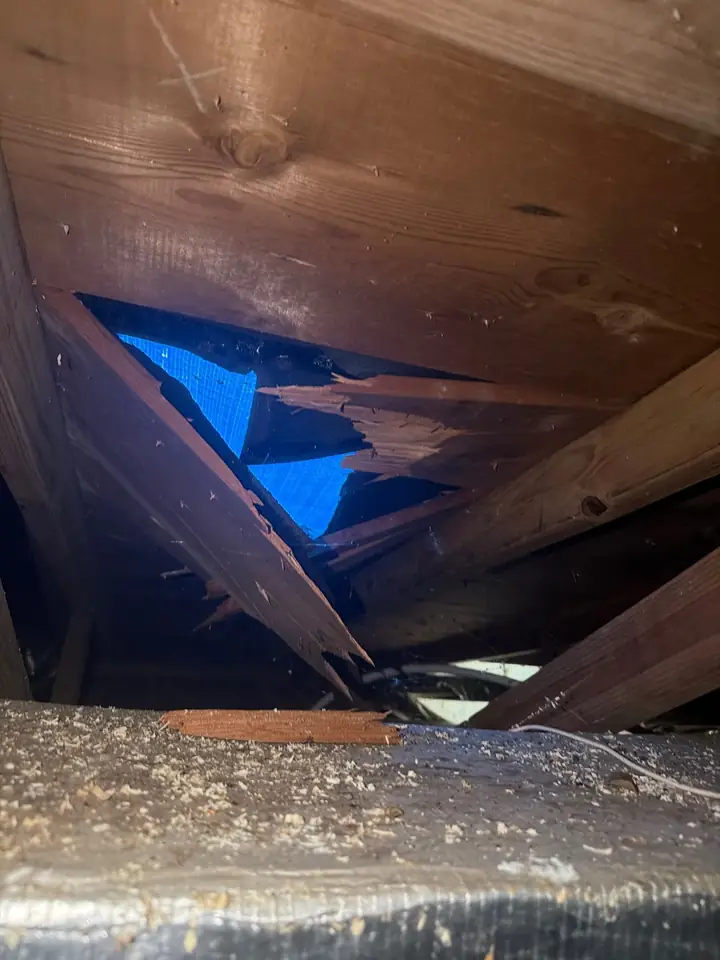
from storms and tornadoes. Insurers often argue wear and tear; dated photos and an inspection soon after the storm help. See roof claims.
where the question is sudden versus long-term leakage. See pipe bursts.
common in Central Florida thunderstorms, where electronics and HVAC damage need a clear cause. See lightning and surge claims.
including business income and loss of rents if your policy has them.
Before you file in Orlando
Three steps make the biggest difference to what a claim can pay.
- Document first, while taking reasonable steps to prevent more damage.
- Read the declarations page for deductibles, including any hurricane deductible, and any roof payment schedule.
- Call us before a recorded statement or accepting a scope, so the claim is described accurately from the start.
Orlando is covered statewide from Hollywood
J Consultants Inc. d/b/a Florida Public Adjusting handles property claims statewide, including Orlando and Orange County. Our only office is in Hollywood.
Claims we handle in Orlando
Residential, condo and commercial claims, including denials and underpayments.
Florida limits public adjuster fees to 10% of claim payments on claims from a declared state of emergency (during the year after the declaration) and 20% on other claims, and lets you cancel a new contract within the period set by s. 626.854, Fla. Stat. We charge no fee unless you get paid, and the fee is agreed in writing before work starts. See public adjuster fees in Florida. General information, not legal advice.
Your adjuster: Joshua Solomon
Florida licensed public adjuster, Lic. W106037
Joshua works for property owners, never for the insurer. J Consultants Inc. d/b/a Florida Public Adjusting holds the firm license, W805707, from our office at 2206 Hollywood Blvd, Hollywood, FL 33020. You pay no fee unless you get paid, and the fee is agreed in writing before work starts. Se habla español. About Joshua.
- Firm license W805707J Consultants Inc. d/b/a Florida Public Adjusting. Verify on the Florida DFS licensee search
- Adjuster license W106037Joshua Solomon. Verify on the Florida DFS licensee search
Florida Public Adjusting · Joshua Solomon, Lic. W106037 · firm Lic. W805707
Orlando: what owners ask
Do hurricanes really damage homes in Orlando?
Is the hurricane deductible different from my regular deductible?
Do you have an Orlando office?
Can you help after the insurer already paid?
Sources: s. 627.701, Fla. Stat. (hurricane deductibles) · s. 627.70132, Fla. Stat. (deadlines to report property claims) · s. 626.854, Fla. Stat. (public adjusters) · Florida DFS licensee search (W805707, W106037)
Roof, water or fire loss in Central Florida?
Call us before you accept a payment or sign a release. A licensed public adjuster calls you back.
J Consultants Inc. d/b/a Florida Public Adjusting, firm Lic. W805707. General information, not legal advice.