Florida · Water damage insurance claims
Water damage insurance claim? Don’t wait. Get the money you are owed.
Call a licensed Florida public adjuster before you file. We have recovered over $100 million for Florida property owners. No fee unless you get paid.
- Call before you file, so the loss is documented correctly from day one
- Already filed, denied or underpaid? We can still help
- Licensed Florida public adjusters who work for you, not the insurance company
- No fee unless you get paid
Get a free claim review
Tell us what happened. A licensed public adjuster calls you back.
- Licensed in FloridaFirm Lic. W805707 · Adjuster Lic. W106037 · verify at DFS
- $100M+ recoveredfor Florida property owners
- No fee unless you get paidFee agreed in writing first
- 25+ years combined experiencewith Florida insurance companies
- 4.8/5 Google ratingRead our Google reviews
- Se habla españolHablamos español. Call (305) 964-8624
Call us before you file your water damage claim
The first statement you give and the first photos you take shape the whole claim. We start there, then handle the insurance company for you.
Call us
Tell us what happened, even if you have not reported the loss yet. Call (305) 964-8624 or use the form above.
We document and build the claim
We inspect the damage, read your policy, and prepare the estimate and supporting documents, including hidden damage behind walls and under floors.
We negotiate until it is resolved
We deal with the insurance company for you and push for a fair settlement. No fee unless you get paid.
Already filed? Denied? Paid less than the repairs cost? Call anyway. We review the estimate, the denial letter and the policy to see what can still be supplemented, reopened or challenged. See also denied and underpaid claims.
Maximum payout for your water damage claim
Flood and water damage can strike just about anywhere, at any time. As a Florida property owner you can face many different types of water damage, and we can help with your water damage insurance claim.
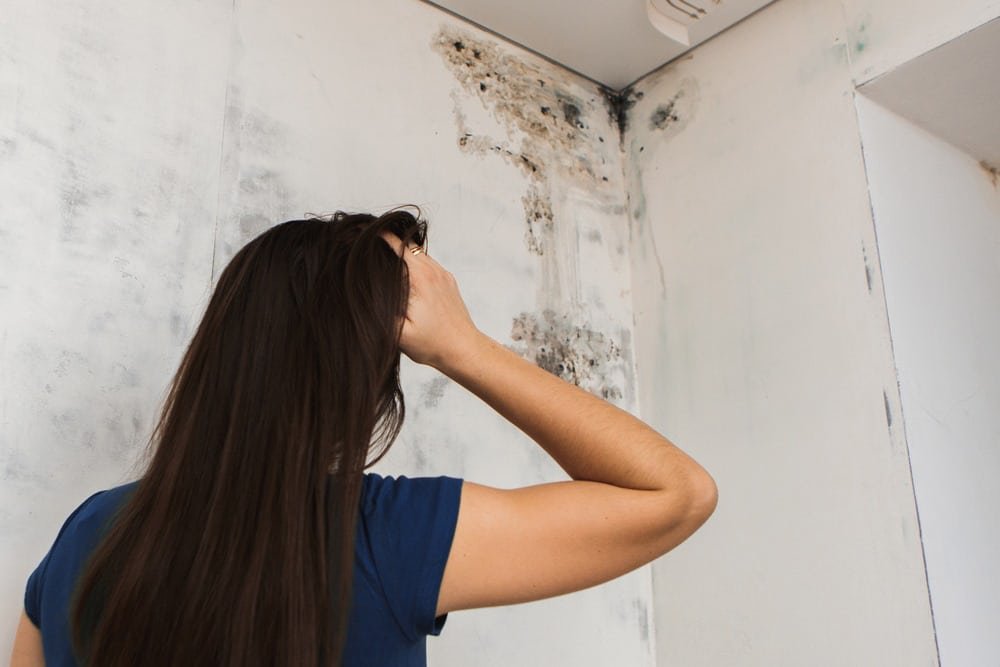
Water damage is common and will ruin wood fixtures, electronics, flooring, carpet, furniture, baseboards, finishing, and bedding. Losses from water exposure are so prevalent that insurers report them as the most frequent claim type they see. Common claims, per insurance company reports:
- Roof leaks and ceiling leaks
- Ceiling damage
- Sewer line damage
- Water heater bursts
- Broken drain lines
- Broken supply lines
- Broken angle stops
- A/C unit leaks
- Mold damage and mold removal
Including
- Refrigerator and appliance leaks
- Water damage mold clean-up claims
- Sewage overflow or backup
- General plumbing mishaps and kitchen plumbing leaks
- Bathroom water damage and mold removal
- Roof leak water damage
If you live in South Florida, water damage in Miami and the surrounding area is quite common and can show up often. Hire a Public Adjuster today. More detail: water leak claims, appliance leaks, water heater leaks, slab leaks, mold claims.
What water damage does Florida homeowners insurance cover?
Most Florida policies cover sudden and accidental water damage. How the water entered your home, how fast you report it, and how the carrier classifies the loss decide whether your claim is approved, underpaid, or denied.
Commonly covered
- Burst or leaking pipes and plumbing failures. The resulting damage and the cost to access the pipe are usually covered (the pipe itself is not).
- Appliance failures: dishwashers, refrigerators, washing machines, water heaters.
- Roof leaks caused by a storm or other covered event.
- Overflows and accidental discharges.
Commonly denied or excluded
- Gradual leaks and long-term seepage the carrier calls “neglect”.
- Rising water from outside. That is flood, a separate policy.
- Mold that the insurer says resulted from an uncovered cause or delayed reporting.
Florida carriers scrutinize water claims hard. Heavy rain, hurricanes, high humidity, and older plumbing give them plenty of angles. If the classification of your loss is wrong, your payout is wrong. We document the damage, read the policy, and file it under the right coverage.
Common insurance claim problems we resolve
Many Florida property owners contact us after realizing the insurance company’s estimate does not match the real cost of repairs. That gap can happen for many reasons.
The insurance estimate is too low
Low estimates are common when the adjuster misses hidden damage, uses outdated pricing, excludes necessary labor, or writes for patch repairs when larger repairs are needed.
The water damage was minimized
Water damage often spreads behind walls, under flooring, into cabinets, and through insulation. If the claim only includes visible stains, it may not reflect the real damage.
The roof claim was denied
Roof claims are often denied because the carrier blames wear and tear, age, installation issues, or prior damage. We review storm evidence, roof conditions, interior leaks, photos, repair estimates, and policy language.
Mold was excluded or ignored
Mold claims require careful documentation. If mold developed from a covered water loss, the cause, timing, moisture source, and remediation needs must be clearly supported.
The claim is delayed
If the insurance company keeps asking for more documents, scheduling repeat inspections, or failing to provide clear answers, a public adjuster can help organize the claim and push the process forward.
The claim was denied
A denial does not always mean the claim is over. Florida Public Adjusting can review the denial letter, policy, inspection notes, and missing evidence to determine whether the claim can be challenged, reopened, or supplemented.
What our clients say
4.8out of 5 Google rating
Source: Florida Public Adjusting Hollywood, Google Business Profile.
“Josh and the rest of the team at Florida Public Adjusting really showed how they care for their clients. My entire kitchen cabinetry was infested with mold. I reached out to Florida Public Adjusting, and let me tell you, they did not disappoint! Josh ensured that my insurance pay me for the removal, restoration, and much more. Very transparent, honest, and most important of all a great public adjuster!”
Eli Benmergui · Google review
“Huge thanks to FLPA in Hollywood for their incredible help after Hurricane Helene. They took the stress out of the flood insurance claim process and made sure I got a fair settlement. Highly recommend them if you want professional experts in your corner!”
Alain B · Google review
¿Daños por agua en su propiedad? Se habla español
Somos Florida Public Adjusting, una firma de ajustadores públicos con licencia en Florida. Representamos a los dueños de la propiedad, no a la compañía de seguros.
Llámenos antes de presentar su reclamo. También podemos ayudarle si su reclamo ya fue presentado, fue negado o le pagaron menos de lo que cuestan las reparaciones. Le atendemos en español.
Sin cargo a menos que usted cobre. La firma tiene la licencia W805707 y el ajustador público Joshua Solomon tiene la licencia W106037 del Departamento de Servicios Financieros de Florida.
Llámenos antes de presentar su reclamo.
Llame al (305) 964-8624Water damage claims explained
This short walkthrough covers the same ground as this page.
Who will handle my claim?
Joshua Solomon, Florida licensed public adjuster, Lic. W106037
J Consultants Inc. d/b/a Florida Public Adjusting, firm Lic. W805707
2206 Hollywood Blvd, Hollywood, FL 33020
Both licenses can be checked on the Florida DFS licensee search. About Joshua · About the firm.
Fees
We charge no fee unless you get paid, the fee is agreed in writing before work starts, and we work to get you a bigger settlement. Florida limits public adjuster fees to 20% of claim payments, or 10% on claims from a declared state of emergency during the year after the declaration (s. 626.854, Fla. Stat.). See public adjuster fees in Florida. General information, not legal advice.
Water damage claims: common questions
What is a public adjuster?
What does a public adjuster do on a water damage claim?
When should I hire a public adjuster?
Can a public adjuster help after my water damage claim was denied?
Can a public adjuster help with an underpaid claim?
Do you handle roof leak and hurricane water damage claims?
Do you handle mold damage claims?
Do you help condo owners and associations?
Do you handle commercial water damage claims?
How much does it cost to hire Florida Public Adjusting?
Is Florida Public Adjusting licensed?
Can I still hire a public adjuster if the insurance company already inspected my property?
What should I do before accepting an insurance settlement?
What areas do you serve?
¿Atienden en español?
Sources
Talk to a licensed public adjuster about your water damage claim
Call before you file, or get help with a denied or underpaid claim.
J Consultants Inc. d/b/a Florida Public Adjusting, firm Lic. W805707. General information, not legal advice.